A rejected mortgage (KPR) application has become a common complaint among home buyers. Real Estat Indonesia (REI) recently said that most KPR applications fail on the ground, especially in the subsidized housing segment. The good news is that many causes of rejection can be prevented or fixed before you apply. This article covers the most common causes, how to fix them, and what to do if your application has already been rejected.
Banks basically assess two things: your ability to pay and your willingness to pay. Ability to pay is based on income, existing installments, and job or business stability. Willingness to pay is based on your credit history. If either is considered risky, the application may be rejected or the loan amount reduced. If you are new to the process, start with our KPR guide from definition to application flow.
These are the causes that come up most often:
Most of the causes above can be prepared for well before you apply:
Rejection by one bank does not mean you cannot get a KPR at all. Steps you can take:
When buying a home in a Damai Putra Group project, the Marketing Gallery team can help simulate installments and explain which documents to prepare before you apply for a KPR. That way you can choose a unit that fits your budget from the start, for example in Kota Harapan Indah or Tera Damai. KPR approval remains the bank's decision, but good preparation makes your chances much better.
Is a rejected KPR recorded in SLIK OJK?
SLIK OJK records credit facilities and their payment history. A rejected application does not create arrears, so what matters is keeping your existing installments current.
How long should I wait before applying again?
There is no fixed rule. It is more important to fix the cause of rejection first, such as paying off arrears or completing documents, and then reapply.
Can paylater cause a KPR rejection?
Yes. Paylater is a credit facility recorded in SLIK OJK, so any arrears are assessed by the bank.
Is it harder for entrepreneurs to get a KPR?
Not necessarily, as long as income can be proven with bank statements, financial records, and complete business legal documents.
For more information about KPR simulations and home options at Damai Putra Group, contact Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.
How Banks Assess a KPR Application
Banks basically assess two things: your ability to pay and your willingness to pay. Ability to pay is based on income, existing installments, and job or business stability. Willingness to pay is based on your credit history. If either is considered risky, the application may be rejected or the loan amount reduced. If you are new to the process, start with our KPR guide from definition to application flow.
7 Most Common Reasons a KPR Is Rejected
These are the causes that come up most often:
- Problematic credit history in SLIK OJK. Late payments on vehicle loans, credit cards, paylater, or online loans are recorded in SLIK OJK. A non-current collectibility status makes banks hesitant, even when the overdue amount is small.
- Debt-to-income ratio too high. Banks usually cap total installments, including existing ones, at around 30 to 40 percent of monthly income. The exact limit differs by bank.
- Income is hard to prove. Employees without official payslips, or entrepreneurs and freelancers without tidy bank statements and financial records.
- Not long enough in the job or business. Many banks require at least 1 to 2 years of employment, or a business that has run for at least 2 years.
- Incomplete documents or inconsistent data. For example, different name spellings on the ID card and family card, an outdated marital status, or an inactive tax ID.
- Age plus tenor exceeds the limit. Banks usually want the KPR paid off before retirement age for employees, or before a certain age for entrepreneurs.
- Appraisal value below the house price. The loan is based on the bank's valuation, so the gap must be covered with a larger down payment. This is not a full rejection, but it often makes the purchase fall through.
How to Get Your KPR Approved
Most of the causes above can be prepared for well before you apply:
- Check your SLIK OJK first. Make sure there are no forgotten arrears, including rarely used paylater and credit cards. See our guide to checking SLIK OJK online.
- Pay off or reduce small installments. Closing consumer loans before applying gives you more room in your debt-to-income ratio.
- Close unused credit limits. Some banks count credit card and paylater limits, not only the outstanding balance.
- Organize your proof of income. Entrepreneurs and freelancers should use one main account for business income. Full tips are in KPR requirements for entrepreneurs and freelancers.
- Prepare a larger down payment. A larger DP lowers the loan amount and installment, which raises your chance of approval. See also down payment rules for KPR.
- Consider joint income. Husband and wife incomes can be combined so the bank assesses a higher ability to pay.
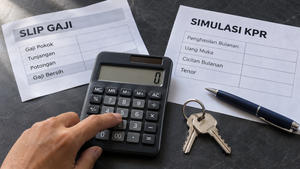
- Simulate installments realistically. Calculate a safe installment with the KPR calculator, then choose a house price and tenor that fit.
Already Rejected? Here Is What You Can Do
Rejection by one bank does not mean you cannot get a KPR at all. Steps you can take:
- Ask for the reason. Banks do not always explain in detail, but officers can usually give general direction.
- Fix the cause first. Do not reapply to many banks at once before the problem is resolved.
- Apply to another bank. Assessment policies differ between banks, so a profile rejected by one bank may be accepted by another.
- Adjust your choice of home. If the issue is the loan amount, choose a type with a more suitable price or increase your DP.
Consult Before You Apply
When buying a home in a Damai Putra Group project, the Marketing Gallery team can help simulate installments and explain which documents to prepare before you apply for a KPR. That way you can choose a unit that fits your budget from the start, for example in Kota Harapan Indah or Tera Damai. KPR approval remains the bank's decision, but good preparation makes your chances much better.
Frequently Asked Questions
Is a rejected KPR recorded in SLIK OJK?
SLIK OJK records credit facilities and their payment history. A rejected application does not create arrears, so what matters is keeping your existing installments current.
How long should I wait before applying again?
There is no fixed rule. It is more important to fix the cause of rejection first, such as paying off arrears or completing documents, and then reapply.
Can paylater cause a KPR rejection?
Yes. Paylater is a credit facility recorded in SLIK OJK, so any arrears are assessed by the bank.
Is it harder for entrepreneurs to get a KPR?
Not necessarily, as long as income can be proven with bank statements, financial records, and complete business legal documents.
For more information about KPR simulations and home options at Damai Putra Group, contact Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.