Bank Indonesia has raised its benchmark interest rate again. If you are planning to buy a home with a KPR, it is natural to wonder: should you buy now, or wait for rates to fall? This article explains the impact on KPR, the simple math, and strategies to help you still buy a home with safe, manageable installments.
Bank Indonesia's Board of Governors Meeting on 17-18 November 2026 decided to raise the BI-Rate by 25 basis points to 6%. The Deposit Facility rate rose to 5.25% and the Lending Facility rate to 6.75%.
This is the fourth increase in 2026. Since May, the BI Rate has risen by a total of 125 basis points, from 4.75% to 6%. According to Bank Indonesia, the increase aims to strengthen rupiah exchange rate stability amid global uncertainty, while keeping 2026 to 2027 inflation within the 2.5±1% target.
The BI Rate is a benchmark rate, not the KPR rate itself. Each bank sets its own KPR rates, and adjustments usually do not happen immediately. The impact depends on your position:
As an illustration, here are monthly installments for a Rp900 million KPR over 20 years:
Over the past six months, the BI Rate has moved in only one direction: up. No one can be sure when this trend will reverse, whether next year or later. Waiting for rates to fall means betting on timing that cannot be predicted, while some costs keep running:
In Kota Harapan Indah, Damai Putra Group offers down payment subsidies and free VAT and BPHTB in selected clusters, subject to applicable terms. If you want to sign soon and lock in a rate sooner, ready stock units are available at Albasia and Hoshi. The Marketing Gallery team can also prepare installment simulations under several rate scenarios, so you can decide with confidence.
What is the latest BI Rate?
6%, based on the Bank Indonesia Board of Governors Meeting on 17-18 November 2026.
Do KPR rates rise immediately after the BI Rate goes up?
Not always. Each bank adjusts its rates according to its own policy. A KPR still in its fixed-rate period is not affected until that period ends.
Should I delay buying a home until rates fall?
Not necessarily beneficial. The timing of a rate cut cannot be predicted, while rent keeps running and developer promotions may be missed. If rates fall later, the KPR can still be taken over by another bank.
How can I reduce the impact of rising KPR rates?
Choose a longer fixed-rate period, prepare a larger down payment, consider ready stock units to sign sooner, and take advantage of developer promotions.
For more information about KPR simulations and homes in Kota Harapan Indah, contact the Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.
BI Rate Rises to 6%: What Was Decided?
Bank Indonesia's Board of Governors Meeting on 17-18 November 2026 decided to raise the BI-Rate by 25 basis points to 6%. The Deposit Facility rate rose to 5.25% and the Lending Facility rate to 6.75%.
This is the fourth increase in 2026. Since May, the BI Rate has risen by a total of 125 basis points, from 4.75% to 6%. According to Bank Indonesia, the increase aims to strengthen rupiah exchange rate stability amid global uncertainty, while keeping 2026 to 2027 inflation within the 2.5±1% target.
How Does It Affect KPR?
The BI Rate is a benchmark rate, not the KPR rate itself. Each bank sets its own KPR rates, and adjustments usually do not happen immediately. The impact depends on your position:
- Borrowers still in a fixed-rate period: installments do not change until the fixed period ends.
- Borrowers on a floating rate: installments may rise if the bank adjusts its rate.
- Buyers who have not signed yet: the fixed promotional rates banks offer today may be adjusted going forward.
How Much Does It Affect Installments?
As an illustration, here are monthly installments for a Rp900 million KPR over 20 years:
- 7% interest: about Rp6.98 million
- 7.5% interest: about Rp7.25 million
- 8% interest: about Rp7.53 million
Buy Now or Wait for Rates to Fall?
Over the past six months, the BI Rate has moved in only one direction: up. No one can be sure when this trend will reverse, whether next year or later. Waiting for rates to fall means betting on timing that cannot be predicted, while some costs keep running:
- Rent keeps going out. For example, with rent of Rp3 million per month, waiting one year means Rp36 million spent without building an asset.
- Developer promotions are limited. Programs such as down payment subsidies and free VAT and BPHTB are not always available.
- A rate locked in now does not trap you if rates fall later. When rates drop in the future, you can still consider a KPR take over to another bank with a lower rate.
Strategies to Keep Installments Safe
- Choose a longer fixed-rate period so installments are more predictable. Compare offers from several banks before signing.
- Prepare a larger down payment to reduce the loan amount. See How Much Is the Down Payment on a House?.
- Consider a ready stock home. Completed homes can usually proceed to KPR signing faster, so you can lock in the rate on offer sooner. See Ready Stock vs Off-Plan Homes.
- Take advantage of developer promotions, such as down payment subsidies and free VAT and BPHTB, to ease upfront costs. A cost breakdown is available in Home Buying Costs 2026.
- Leave room in your budget. Ideally, installments should not exceed about 30% of income, so you stay comfortable if a floating rate rises later.
Home Options in Kota Harapan Indah
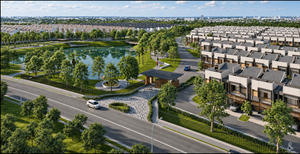
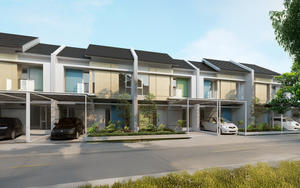
In Kota Harapan Indah, Damai Putra Group offers down payment subsidies and free VAT and BPHTB in selected clusters, subject to applicable terms. If you want to sign soon and lock in a rate sooner, ready stock units are available at Albasia and Hoshi. The Marketing Gallery team can also prepare installment simulations under several rate scenarios, so you can decide with confidence.
Frequently Asked Questions
What is the latest BI Rate?
6%, based on the Bank Indonesia Board of Governors Meeting on 17-18 November 2026.
Do KPR rates rise immediately after the BI Rate goes up?
Not always. Each bank adjusts its rates according to its own policy. A KPR still in its fixed-rate period is not affected until that period ends.
Should I delay buying a home until rates fall?
Not necessarily beneficial. The timing of a rate cut cannot be predicted, while rent keeps running and developer promotions may be missed. If rates fall later, the KPR can still be taken over by another bank.
How can I reduce the impact of rising KPR rates?
Choose a longer fixed-rate period, prepare a larger down payment, consider ready stock units to sign sooner, and take advantage of developer promotions.
For more information about KPR simulations and homes in Kota Harapan Indah, contact the Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.