When taking out a mortgage (KPR), many people focus on the down payment and the first month's instalment. Yet what shapes the total cost of a home over ten to twenty years or more is the mortgage interest rate, especially what happens once the promotional rate period ends.
This article explains the types of mortgage interest in Indonesia, how floating rates are set, why instalments can rise, and what to check before signing the loan agreement.
1. Fixed rate
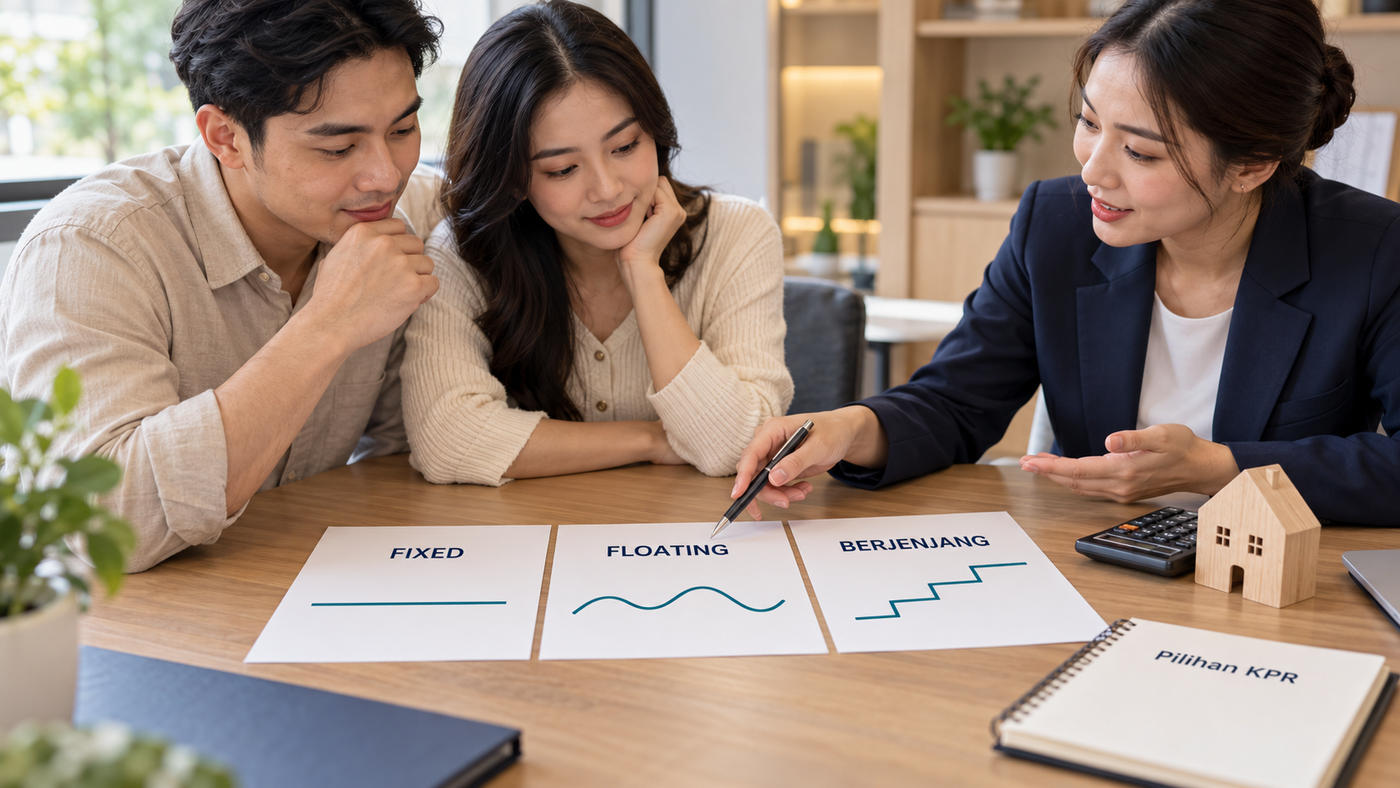
The rate stays the same for a set period, such as the first 1, 3, or 5 years. Instalments during that period do not change, making them easy to plan for. Once the fixed period ends, the rate usually switches to floating.
2. Floating rate
The rate follows market conditions and the bank's policy, so it can go up or down. As a result, instalments can also change over time.
3. Tiered (stepped) rate
The rate is set in stages. For example, a low rate in years 1 to 3, a higher rate in years 4 to 6, then a further increase or a switch to floating. Instalments start lighter and rise on a schedule known from the start.
4. Fixed cap (capped) rate
A combination of three stages: a fixed period at the start, then a floating period with a ceiling (the rate may rise but not above a set level), followed by a fully floating period with no cap.
Each bank offers different combinations, so read the details of each product carefully.
Floating rates are not set at random. Several reference points influence them:
The BI Rate. Bank Indonesia's benchmark rate affects banks' cost of funds. As of the Board of Governors meeting on 20 to 21 October 2026, the BI Rate stood at 5.75%, up from 4.75% at the start of 2026. A higher BI Rate does not automatically change mortgage rates straight away, but over the medium term it can push floating rates up.
The SBDK (Base Lending Rate). Conventional commercial banks must publish their SBDK, including for the mortgage segment, under OJK Regulation Number 13 of 2024. The SBDK is built from the bank's cost of funds, overhead costs, and profit margin. The rate charged to a borrower is not necessarily the same as the SBDK, as a risk premium may be added.
The formula in the loan agreement. Some banks state the floating rate formula in their product documents, for example the BI Rate plus a set margin. This is the formula you need to find and understand.
Most mortgages in Indonesia use the annuity method. The monthly instalment stays the same as long as the rate does not change, but its make-up differs: early in the loan, the interest portion is much larger than the principal portion.
Illustrative example: a Rp 800 million loan over 20 years at 5%. The instalment is about Rp 5.28 million a month. In the first month, about Rp 3.33 million is interest and only about Rp 1.95 million reduces the principal.
This is why partial prepayment in the early years can noticeably reduce total interest, as long as the penalty fee is taken into account.
The jump in instalments after the fixed period is what most often catches borrowers off guard. Here is an illustration:
A Rp 800 million loan over 20 years, with a fixed rate of 5% for the first 3 years.
Years 1 to 3 (fixed 5%): instalment of about Rp 5.28 million a month.
Year 4 onwards, if floating at 10%: about Rp 7.40 million a month.
If floating at 11%: about Rp 7.86 million a month.
If floating at 12%: about Rp 8.34 million a month.
In other words, instalments can rise by around 40% to 58% once the fixed period ends.
The figures above only illustrate an annuity calculation and are not any particular bank's offer. Actual rates depend on the bank, the product, and your profile.
To calculate with your own figures, use the 2026 Mortgage Calculator.
1. Look beyond the promotional rate. Ask what floating rate applies after the fixed period ends, and how the bank calculates it.
2. Read the RIPLAY. Banks must provide a RIPLAY (Product and Service Information Summary). It usually sets out the rate scheme, fees, late payment penalties, and prepayment penalties.
3. Calculate your instalment in a worst-case scenario. Make sure you can still pay if the floating rate rises by a few percent. Many banks cap instalments at around one third of income, so leave yourself some headroom.
4. Consider a longer fixed period. A longer fixed period usually carries a slightly higher rate, but gives certainty for longer. This suits borrowers with stable income who want to avoid surprises.
5. Check the early repayment penalty. Many banks charge a penalty as a percentage of the amount repaid, and some require a minimum tenor for certain promotional products.
6. Build an emergency fund. A financial buffer helps you stay safe when instalments rise.
7. Know your take over option. If the floating rate becomes a burden, you can consider moving your mortgage to another bank. The pros and cons are covered in Mortgage Take Over.
Besides interest, a mortgage comes with costs such as provision fees, administration fees, appraisal, life and fire insurance, and notary fees. These are covered in The Cost of Buying a House in 2026. Before applying, also check your credit history through SLIK OJK, and read the full steps in the 2026 Mortgage Guide.
A rate scheme is best considered together with the home itself. Damai Putra Group areas offer options across different instalment ranges, such as the Feia cluster in Segara City, with instalments from around Rp 3 million, and Navara in Kota Harapan Indah, with instalments from around Rp 6 million. Ask which rate scheme and partner bank are used in the simulation. Promotion terms may change at any time.
What is the difference between fixed and floating rates?
A fixed rate stays the same for a set period, so instalments are stable. A floating rate follows market conditions and bank policy, so instalments can rise or fall.
Why do mortgage instalments rise after a few years?
Usually because the fixed rate period has ended and the rate has switched to a higher floating rate.
Do mortgage rates fall when the BI Rate falls?
Not always straight away. The BI Rate affects banks' cost of funds, but floating rate adjustments depend on each bank's policy and the formula in the loan agreement.
What is a tiered rate?
A rate scheme that rises in stages on a schedule set from the start, for example lower in the first years and higher in later periods.
Where can I see a bank's mortgage rate details?
In the bank's mortgage RIPLAY, and in the SBDK published on the bank's official website.
This article is general information and not financial advice. Interest rates, fees, and mortgage terms differ between banks and may change, so please confirm the details directly with the bank.
For more information about Damai Putra Group homes and mortgage simulations, contact the Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.
This article explains the types of mortgage interest in Indonesia, how floating rates are set, why instalments can rise, and what to check before signing the loan agreement.
Types of Mortgage Interest
1. Fixed rate
The rate stays the same for a set period, such as the first 1, 3, or 5 years. Instalments during that period do not change, making them easy to plan for. Once the fixed period ends, the rate usually switches to floating.
2. Floating rate
The rate follows market conditions and the bank's policy, so it can go up or down. As a result, instalments can also change over time.
3. Tiered (stepped) rate
The rate is set in stages. For example, a low rate in years 1 to 3, a higher rate in years 4 to 6, then a further increase or a switch to floating. Instalments start lighter and rise on a schedule known from the start.
4. Fixed cap (capped) rate
A combination of three stages: a fixed period at the start, then a floating period with a ceiling (the rate may rise but not above a set level), followed by a fully floating period with no cap.
Each bank offers different combinations, so read the details of each product carefully.
How Are Floating Rates Set?
Floating rates are not set at random. Several reference points influence them:
The BI Rate. Bank Indonesia's benchmark rate affects banks' cost of funds. As of the Board of Governors meeting on 20 to 21 October 2026, the BI Rate stood at 5.75%, up from 4.75% at the start of 2026. A higher BI Rate does not automatically change mortgage rates straight away, but over the medium term it can push floating rates up.
The SBDK (Base Lending Rate). Conventional commercial banks must publish their SBDK, including for the mortgage segment, under OJK Regulation Number 13 of 2024. The SBDK is built from the bank's cost of funds, overhead costs, and profit margin. The rate charged to a borrower is not necessarily the same as the SBDK, as a risk premium may be added.
The formula in the loan agreement. Some banks state the floating rate formula in their product documents, for example the BI Rate plus a set margin. This is the formula you need to find and understand.
How Interest Is Calculated: Annuity
Most mortgages in Indonesia use the annuity method. The monthly instalment stays the same as long as the rate does not change, but its make-up differs: early in the loan, the interest portion is much larger than the principal portion.
Illustrative example: a Rp 800 million loan over 20 years at 5%. The instalment is about Rp 5.28 million a month. In the first month, about Rp 3.33 million is interest and only about Rp 1.95 million reduces the principal.
This is why partial prepayment in the early years can noticeably reduce total interest, as long as the penalty fee is taken into account.
Simulation: When the Fixed Period Ends
The jump in instalments after the fixed period is what most often catches borrowers off guard. Here is an illustration:
A Rp 800 million loan over 20 years, with a fixed rate of 5% for the first 3 years.
Years 1 to 3 (fixed 5%): instalment of about Rp 5.28 million a month.
Year 4 onwards, if floating at 10%: about Rp 7.40 million a month.
If floating at 11%: about Rp 7.86 million a month.
If floating at 12%: about Rp 8.34 million a month.
In other words, instalments can rise by around 40% to 58% once the fixed period ends.
The figures above only illustrate an annuity calculation and are not any particular bank's offer. Actual rates depend on the bank, the product, and your profile.
To calculate with your own figures, use the 2026 Mortgage Calculator.
Tips for Choosing a Mortgage Rate Scheme
1. Look beyond the promotional rate. Ask what floating rate applies after the fixed period ends, and how the bank calculates it.
2. Read the RIPLAY. Banks must provide a RIPLAY (Product and Service Information Summary). It usually sets out the rate scheme, fees, late payment penalties, and prepayment penalties.
3. Calculate your instalment in a worst-case scenario. Make sure you can still pay if the floating rate rises by a few percent. Many banks cap instalments at around one third of income, so leave yourself some headroom.
4. Consider a longer fixed period. A longer fixed period usually carries a slightly higher rate, but gives certainty for longer. This suits borrowers with stable income who want to avoid surprises.
5. Check the early repayment penalty. Many banks charge a penalty as a percentage of the amount repaid, and some require a minimum tenor for certain promotional products.
6. Build an emergency fund. A financial buffer helps you stay safe when instalments rise.
7. Know your take over option. If the floating rate becomes a burden, you can consider moving your mortgage to another bank. The pros and cons are covered in Mortgage Take Over.
Costs Beyond Interest
Besides interest, a mortgage comes with costs such as provision fees, administration fees, appraisal, life and fire insurance, and notary fees. These are covered in The Cost of Buying a House in 2026. Before applying, also check your credit history through SLIK OJK, and read the full steps in the 2026 Mortgage Guide.
Matching Instalments to Your Choice of Home
A rate scheme is best considered together with the home itself. Damai Putra Group areas offer options across different instalment ranges, such as the Feia cluster in Segara City, with instalments from around Rp 3 million, and Navara in Kota Harapan Indah, with instalments from around Rp 6 million. Ask which rate scheme and partner bank are used in the simulation. Promotion terms may change at any time.
Frequently Asked Questions
What is the difference between fixed and floating rates?
A fixed rate stays the same for a set period, so instalments are stable. A floating rate follows market conditions and bank policy, so instalments can rise or fall.
Why do mortgage instalments rise after a few years?
Usually because the fixed rate period has ended and the rate has switched to a higher floating rate.
Do mortgage rates fall when the BI Rate falls?
Not always straight away. The BI Rate affects banks' cost of funds, but floating rate adjustments depend on each bank's policy and the formula in the loan agreement.
What is a tiered rate?
A rate scheme that rises in stages on a schedule set from the start, for example lower in the first years and higher in later periods.
Where can I see a bank's mortgage rate details?
In the bank's mortgage RIPLAY, and in the SBDK published on the bank's official website.
This article is general information and not financial advice. Interest rates, fees, and mortgage terms differ between banks and may change, so please confirm the details directly with the bank.
For more information about Damai Putra Group homes and mortgage simulations, contact the Damai Putra Group Marketing Gallery via WhatsApp Official 0811 4466 888 or visit www.damaiputra.com.